 Nigeria is looking for investments of $7 billion in mining and steel over the next decade as it seeks to develop gold and iron ore extraction industries to diversify its oil-dependent economy.
One of the government’s priorities is to meet its annual steel demand of 6.8 million metric tons, from a current output of a third of that, produced mainly from scrap iron, Solid Minerals Development Minister Kayode Fayemi said.
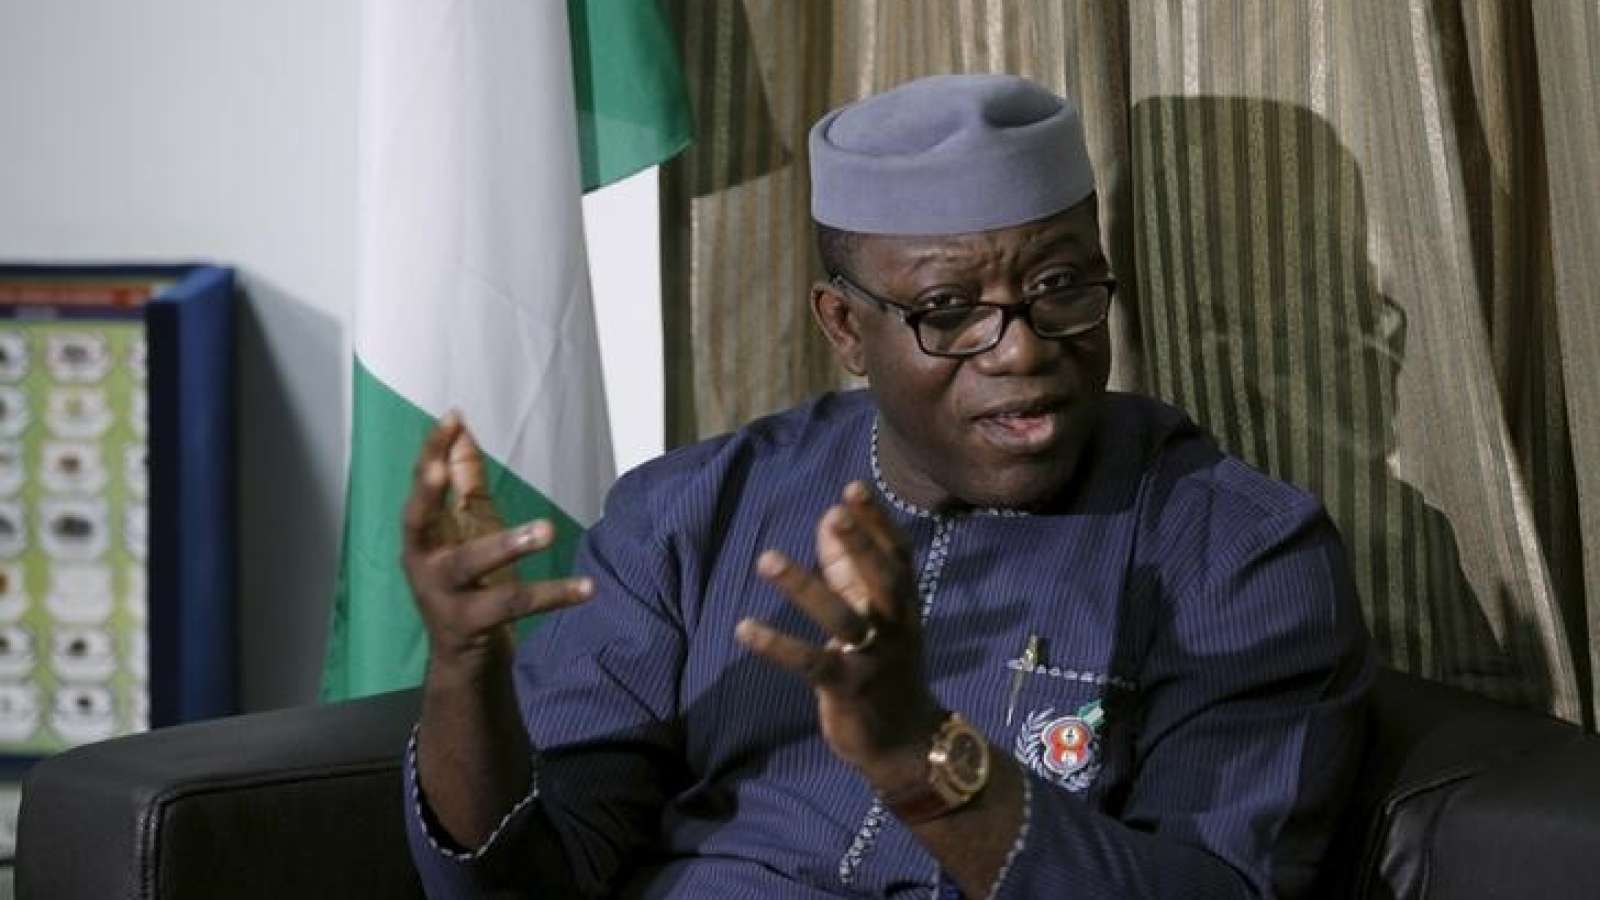
“About $5 billion will kick-start the mining sector,” Fayemi, said in an interview in his Abuja office. “In two to five years, we want to have started production of iron ore, lead, zinc, bitumen, nickel, coal and gold at a serious scale.” Companies considering investments in Nigeria’s mining industry include Lagos-based Multiverse Mining & Exploration and Kogi Iron, based in West Perth Australia, he said.
Boosting mining output, along with developing agriculture and infrastructure, is part of plans to broaden the economy of Africa’s second-largest oil producer. Crude accounts for around 70% of the Organisation of the Petroleum Exporting Countries (OPEC) member’s revenue and for 13% of gross domestic product, according to Finance Minister Kemi Adeosun. Slumping global oil prices, from over $100 a barrel of Brent crude in 2014 to under $50 a barrel currently, and reduced output due to militants attacks on pipelines in Nigeria’s Niger River delta, have squeezed state finances and caused a chronic dollar shortage.
Fayemi will this month present a mining plan to President Muhammadu Buhari and later a bill proposing the creation of a regulator for the sector.
-Bloomberg


 Nigeria is looking for investments of $7 billion in mining and steel over the next decade as it seeks to develop gold and iron ore extraction industries to diversify its oil-dependent economy.

